Commercial real estate buyers are finding openings after several years of repricing, but the case for a deal now depends on the asset and its ability to grow income. That was the central message from a panel at the ULI Fall Meeting in Miami, where investors and researchers weighed higher borrowing costs against resilient operating fundamentals.
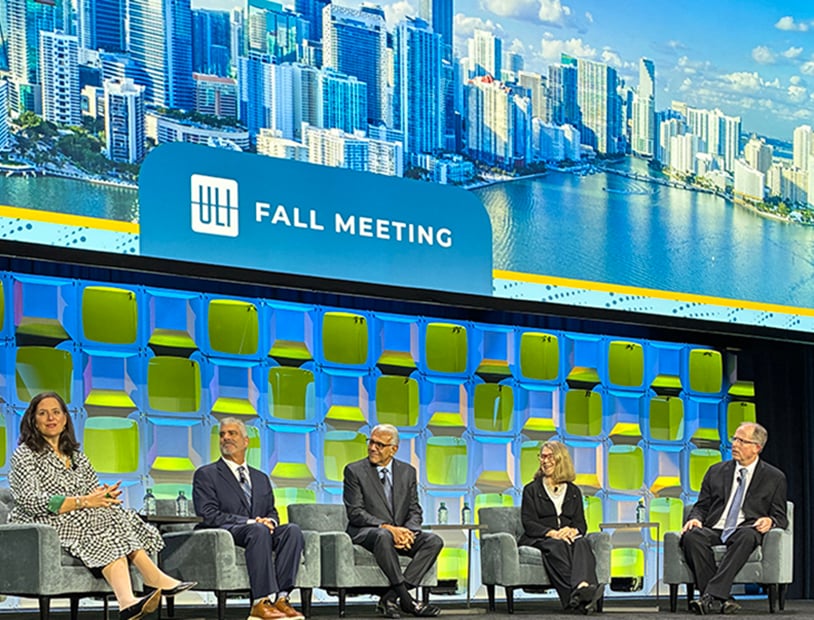
Sara Queen, Oxford Properties’ head of U.S. real estate, described the current market as favorable for both buyers and credit investors—provided they remain selective and manage assets closely. “If you’re disciplined about it, you can find opportunities,” she said.
The discussion, moderated by PwC Partner Andrew Alperstein, addressed findings in the latest Emerging Trends in Real Estate report, themed “You Have to Work For It.” Its themes include underwriting individual assets rather than relying on broad sector or submarket bets, and seeking returns through income gains instead of cap rate compression.
Survey respondents showed their strongest interest in buying real estate in years, Alperstein said, even as their outlook remained cautious. The 10-year Treasury yield was hovering near 5 percent, above the level many had expected after last year’s survey. Panelists were more positive on commercial property than on housing.
Repricing shifts the focus to operations
Mary Ludgin, senior advisor to Heitman, called the recent period a “slog,” but said repricing and a resilient U.S. economy have improved the setup for property owners. She pointed to solid real estate income and managed supply, despite yields on 10-year Treasuries at or above 5 percent.
For Hessam Nadji, president and CEO of Marcus & Millichap, rate volatility is a bigger obstacle than the level of rates alone. Uncertainty about how AI may change real estate business models adds another variable. Nadji said repricing has occurred, but a fuller adjustment may come when lenders sell assets they hold on their books. The result, he said, is a market that feels more confusing yet more optimistic.
Higher financing costs are making deals harder to underwrite, Queen said, and putting greater emphasis on improving existing properties. “Cap rate compression is not going to solve your problems,” she said. “Cheap debt doesn’t.”
Residential conditions are less settled, according to Ken Perlman, managing principal of John Burns Research and Consulting. High rates and inflation are weighing on home purchases and construction. The economy’s K-shaped performance has widened the gap between confident, wealthier buyers and households facing more pressure. Perlman said consumers remain concerned about mortgage rates, oil prices and conflicts abroad.
READ ALSO: Fed Stays the Course as Industry Awaits More Rate Hikes
Capital is choosing markets and property types
Ludgin said Heitman remains positive on the market but is concentrating capital in targeted areas. The firm recently raised a fund dedicated to self storage. “Selective is the word of the day,” she said, describing an environment where decisions turn on individual assets and submarkets.
Retail has changed markedly for Marcus & Millichap’s clients, Nadji said. Consumer spending has helped the sector recover and draw new capital. Office remains a major opportunistic segment, with signs that its recovery can hold. Multifamily, once a favored commercial property type, is facing rent pressure.
The report’s markets to watch are Dallas, Nashville, Miami, Raleigh-Durham, San Francisco, Houston, Manhattan, Jersey City, Tampa/St. Petersburg and Charlotte. Queen cited AI growth as a boost for San Francisco. In Manhattan, Oxford leased the top two floors at 70 Hudson Yards, each measuring 30,000 square feet, for $324 per square foot.
Local policy enters underwriting
“Policy is the new geography” was another report theme discussed by the panel. Investors are paying closer attention to how existing and pending rules affect the feasibility of a property investment. Queen said rent control can fit an investment case when accounted for from the start, but becomes a problem when introduced after underwriting.
For buyers and lenders, the panel’s read is that repricing has opened room to transact, while durable returns will depend on careful asset selection, operating performance and a clear view of local conditions.