If you're a veteran or active-duty service member who's been waiting for the right moment to buy, the current market may give you more leverage than you think. VA loan benefits are already strong. What's changed is the room to use them.
More homes are on the market, and in many areas buyers aren't facing the bidding wars that defined the last few years. That matters for VA borrowers, who have often struggled to get offers accepted in competitive conditions. Here's the thing: much of the reputation VA loans carry doesn't hold up against the data.
What VA Loans Already Offer
Nearly 4 million service members and veterans currently hold an active VA home loan. The Department of Veterans Affairs reported more than 343,000 home purchases using VA loan benefits in its most recent fiscal year. That's a lot of buyers who found the program worth using.
Eligible borrowers get advantages that can make a purchase more affordable:
-
No down payment required for many eligible borrowers.
-
No monthly mortgage insurance, even with no down payment.
-
Competitive mortgage rates that can help lower monthly payments.
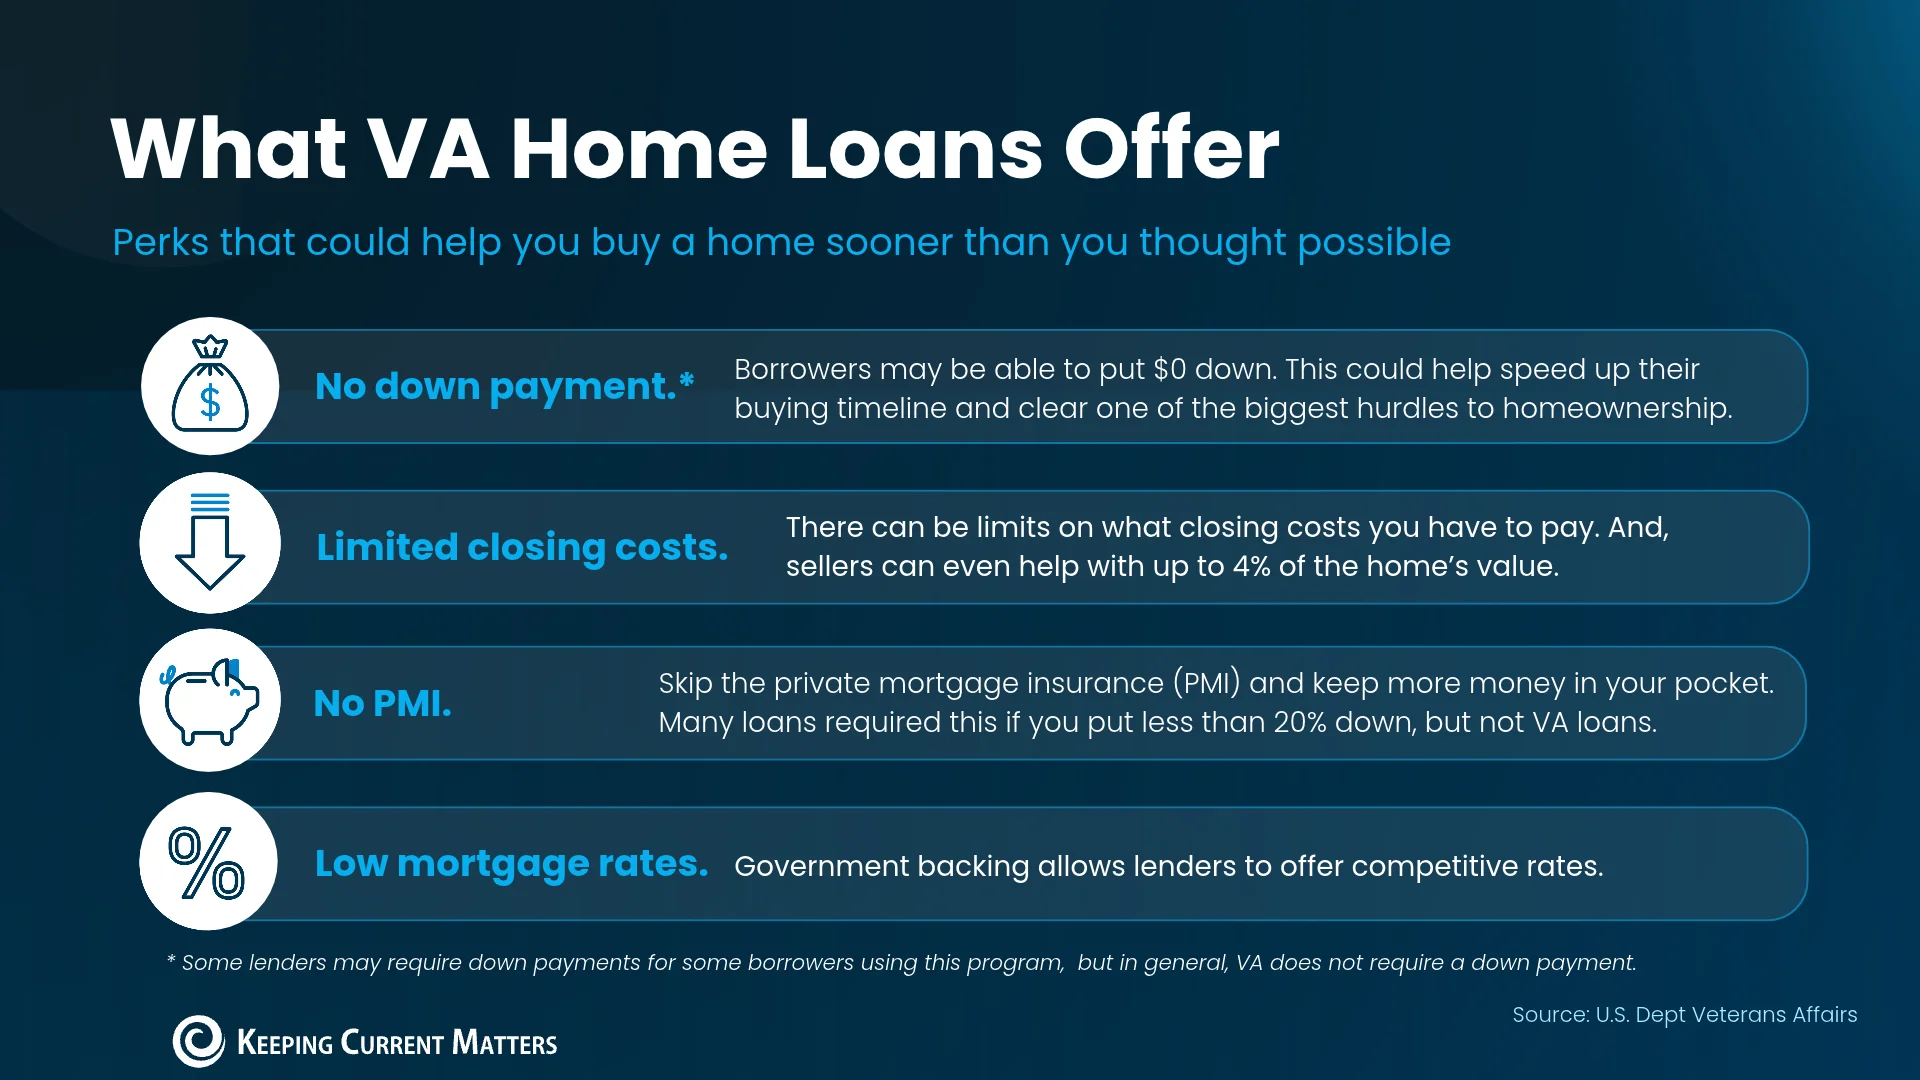
Those advantages hold up in any market, but they stand out more right now. VA loan usage has grown two years running, which suggests more eligible buyers are catching on.
Why Sellers Hesitated
A few years ago, with multiple offers on most listings, VA buyers often lost out. A 2021 survey from the National Association of Realtors found 89% of sellers were likely to accept an offer from a buyer using a conventional loan. Only 30% said the same about an FHA or VA loan.
Sellers' worries centered on three things: slower financing, harder closings, and higher costs for repairs and concessions. Those concerns don't necessarily match how VA loans perform today.
Separating VA Loan Myths From Performance
A white paper from Vetted VA, based on 2025 mortgage data, tested several common assumptions. Four stand out.
Myth #1: VA loans get denied more often than other loans.
-
The reality: VA loans posted the lowest denial rate. Just 8.2% of VA purchase applications were denied, versus 15.0% for conventional loans, 12.8% for FHA and 12.5% for USDA.
Myth #2: VA financing is less reliable.
-
The reality: 90% of VA applications that reached underwriting made it to closing, compared with 81% for conventional loans.
Myth #3: VA appraisals take longer.
-
The reality: VA appraisals typically take 7–10 business days, in line with conventional and FHA loans.
Myth #4: Sellers have to pay all closing costs for VA buyers.
-
The reality: VA buyers can pay many standard closing costs themselves. Buyers and sellers can also negotiate which eligible costs the seller will cover.
More Negotiating Room for VA Buyers
With more inventory and fewer competing buyers in many areas, sellers may be more open to VA financing than they were a few years ago. And winning the offer is only the first step.
Depending on the property and your local market, you may be able to negotiate a lower price, ask for repairs, or request help with closing costs. VA guidelines allow sellers to cover the buyer's normal closing costs, plus concessions of up to 4% of the home's value.
Put those pieces together and the picture changes. A buyer could potentially purchase with no down payment, skip mortgage insurance, and negotiate help with other expenses that come with buying a home. That could leave thousands of dollars in savings instead of spent at closing, which is breathing room you'll feel after you get the keys.
The Practical Next Step
If you're active duty, you've served, or you know someone who has, the most useful move is a conversation with a local agent and a VA-approved lender. They can show you what you qualify for in your specific market. Your VA benefit and today's inventory may be a stronger combination than the older myths suggest.